How Do I Know What Price Range I Should Stay In?
"How much house can I afford?"
I get asked this before I get asked almost anything else.
And here's the thing nobody tells you up front. That question has two different answers. One comes from a lender. One comes from you. They are not always the same number, and mixing them up is how people end up house poor, stressed out, or completely priced out of the process before they even start.
So let's slow down and actually answer it.
What's the Difference Between What I Qualify For and What I Should Spend?
A lender will tell you the maximum you qualify for based on your income, debt, and credit.
That number is not a target. It's a ceiling.
Qualifying for a payment and being comfortable with a payment are two very different experiences. One shows up on paper. The other shows up in your bank account every single month, alongside your car payment, your groceries, your dog's vet bills, and whatever life throws at you that month.
Your real price range lives somewhere below that ceiling, in the space where you can afford your home and still actually live your life.
What Should I Actually Be Looking At Besides the Sale Price?
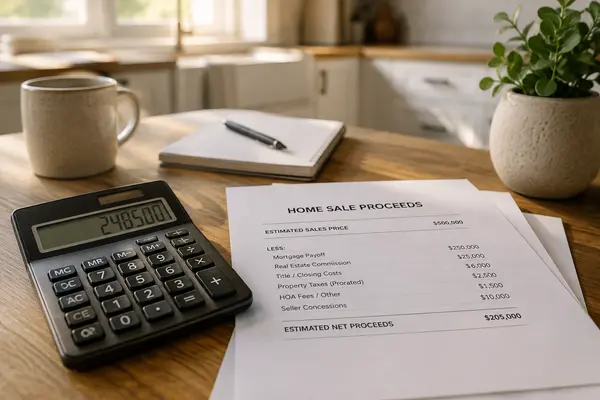
The sale price is just the headline. Your real price range depends on a few moving pieces working together.
Your down payment. More down usually means a lower monthly payment, but it also means less cash in your pocket for moving costs, repairs, or that "oh no the water heater just died" moment.
Your monthly payment comfort zone. Not the number a lender says you can technically handle. The number that lets you sleep at night.
Current interest rates. Rates move the relationship between price and payment more than people expect. The same monthly payment can buy you a very different price range depending on where rates sit when you're shopping.
Closing costs and reserves. Buying a home costs money before you even own the home. Your price range needs room for that too.
Property taxes and insurance. These vary depending on where you land, whether that's East Memphis, Cordova, or across the state line in DeSoto County. They're part of your real monthly number, not an afterthought.
None of these live in isolation. Change one, and the others shift with it.
Should I Just Use an Online Calculator?
Online calculators are a fine starting point. They are not a strategy.
They're built for a generic buyer in a generic market, and you are neither of those things. They don't know your actual debt, your actual comfort level with risk, or what taxes and insurance actually look like in the specific area you're eyeing, whether that's Midtown, Olive Branch, or Southaven.
Think of a calculator as a rough sketch. Getting pre-approved is what turns that sketch into an actual plan.
Why Does Getting Pre-Approved Matter So Much?
Because it turns "I think I can afford this" into "I know exactly what I'm working with."
Pre-approval gives you a real number based on your real financial picture, not a guess pulled from a slider on a website. It also tells sellers you're a serious buyer, which matters more than people realize once you're competing for the home you love.
I always tell my clients the same thing. Get pre-approved before you fall in love with a house, not after. Falling for a home outside your range is one of the fastest ways to talk yourself into a payment you'll regret.
How Do I Know What I'm Actually Comfortable With?
This is the part a lender can't answer for you.
Ask yourself what you want your life to look like around that payment. Do you want room to travel? To save? To not panic every time something breaks?
Your price range should reflect your life, not just your income.
I've watched buyers qualify for one number and choose to buy well below it on purpose, because they wanted breathing room. That's not settling. That's being smart with your money in a market where rates and monthly payments matter just as much as the sale price on the listing.
FAQs
Do I need a large down payment to buy in the Memphis area?
Not necessarily. There are loan programs designed for smaller down payments, especially for first time homebuyers, whether you're buying in Tennessee or Mississippi. Your price range will shift depending on the program you use, which is exactly why this conversation should happen early.
Should I max out what I'm approved for?
Not automatically. Being approved for a number and being comfortable at that number are two different things. Your real price range should leave room for life outside the mortgage.
How do interest rates affect my price range?
Rates directly affect your monthly payment, which means they directly affect how much home fits your budget. The same budget can stretch further or fall short depending on where rates sit when you're ready to buy.
What if I don't know what area I want to buy in yet?
That's normal, and it's actually a good reason to nail down your price range first. Knowing your number narrows the search and helps us figure out which neighborhoods actually fit, whether that ends up being on the Tennessee side or over in DeSoto County.
Is getting pre-approved the same as applying for a mortgage?
Not quite. Pre-approval gives you a real, lender-backed number to shop with. The full mortgage application comes later, once you're under contract on a specific home.
Can my price range change during the home buying process?
It can, especially if rates move or your financial picture shifts. That's exactly why staying in close contact with your lender and your agent throughout the process matters.
Your Price Range Isn't a Number. It's a Decision.
Here's what I want you to walk away with.
Your price range isn't something a website hands you. It's not even something a lender hands you, not really. It's a decision you make on purpose, with real numbers in front of you and your actual life in mind.
Get pre-approved. Know your real comfort zone. Then let's go find the home that fits both, wherever it lands across the Greater Memphis area.
Categories
Recent Posts